HMRC agent authorisation guide for accountants
Which route to use for each tax when a new client joins, whether form 64-8 still works, and what Companies House now expects of your firm. This HMRC agent authorisation guide is one Word reference sheet for you and your team.
UK practices- In the pack
- Client onboarding and disengagement pack
- Files
- 8, Word
Get the pack by email
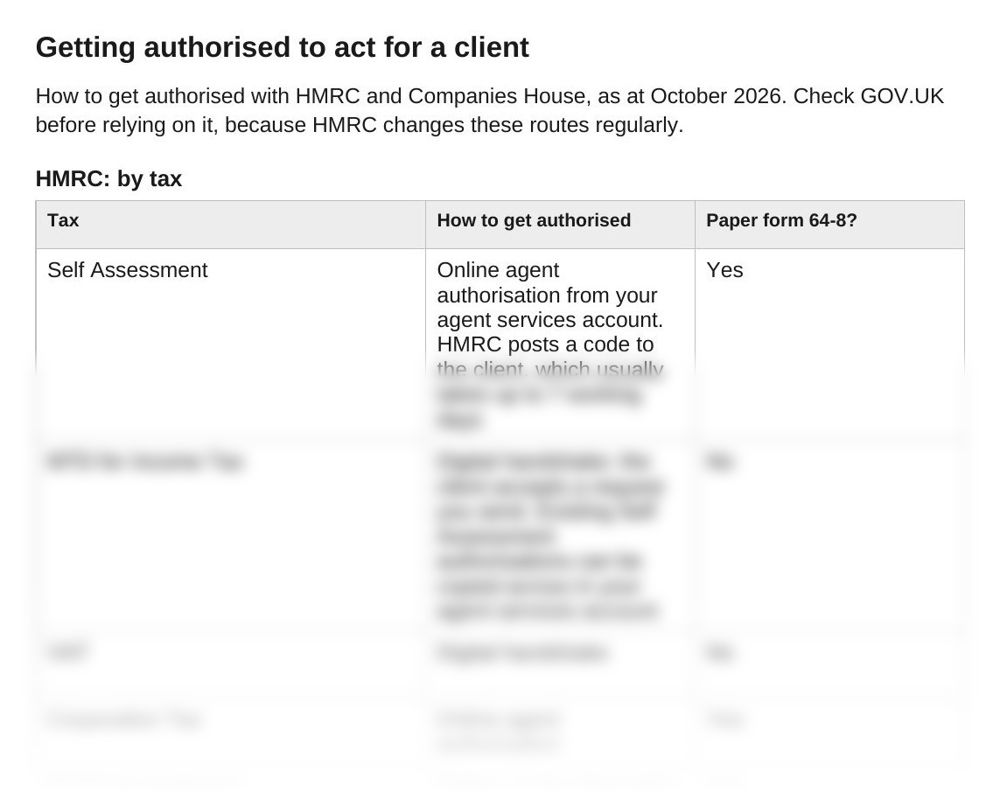
What the guide looks like
When you need it
Before you can deal with HMRC for a client, the client has to authorise you, tax by tax. Keep the guide next to your new client checklist and use it when:
- A new client joins and you need to act for them on each of their taxes
- An existing client adds a tax, such as registering for VAT or taking on employees
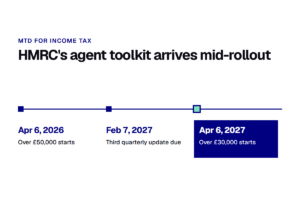
- A Self Assessment client comes into MTD for Income Tax
- A company client appoints a new director who has to verify their identity
- Your firm registers with HMRC as a tax adviser or with Companies House as an authorised agent
How to use the HMRC agent authorisation guide
- List the client's taxes. Use your new client checklist to note every tax and scheme you will deal with.
- Find each one in the table. The HMRC section gives the route for each tax and whether form 64-8 is accepted.
- Send the requests from your agent services account. Use online agent authorisation or the digital handshake as the table shows, and keep a note of what you have asked for.
- Check the Companies House points. Ask for the authentication code, and check whether each director has verified their identity.
- Record what is in place. Note on the client file which authorisations are live, so you can remove them when the client leaves.
Questions
How do I get agent authorisation from HMRC?
Sign in to your agent services account. For Self Assessment, Corporation Tax, PAYE and CIS, use online agent authorisation. For VAT, MTD for Income Tax and the Trust Registration Service, use the digital handshake: choose 'Ask a client to authorise you', enter the client's details, and the client accepts the request.
Is form 64-8 still used?
Yes, for Self Assessment, Corporation Tax, PAYE for employers and individual PAYE and National Insurance matters. It is not accepted for VAT, MTD for Income Tax, CIS or the Trust Registration Service, which are authorised online only.
Do I need an agent services account?
Yes. HMRC counts anyone who deals with it about someone else's tax affairs and gets paid for it as a tax adviser, and tax advisers must register through an agent services account. The firm registers as a legal entity. You have three months from the date your window opens, and you can keep acting for clients during that time and while HMRC considers your registration. Firms that already have an agent services account do not need to register again.
Can I use my client's HMRC sign-in details?
No. HMRC says agents should not use a client's HMRC sign-in details or access their online tax account. Get authorised through your own agent services account instead.
Do accountants need to register with Companies House?
To verify identities for clients, your firm must register as an authorised agent, also called an Authorised Corporate Service Provider. You can only register if you are already supervised by a UK anti-money laundering supervisory body.
When do directors have to verify their identity?
Identity verification has been compulsory for new directors and people with significant control since 18 November 2025. Existing directors give their personal code in their company's next confirmation statement.
Also in the client onboarding and disengagement pack
Who it's for
Sole practitioners and small firms setting up HMRC and Companies House access for new clients.
Last checked
Checked against HMRC and Companies House guidance on GOV.UK in November 2026.