Directors' loan account template (Excel) with section 455 tax
Keep a running record of every amount a director takes out of the company or pays back in, and see straight away whether the year-end balance leads to section 455 tax and when it is due. This directors' loan account template is one Excel workbook with room for 100 entries in the year.
UK practicesGet this pack and 100 more for $129
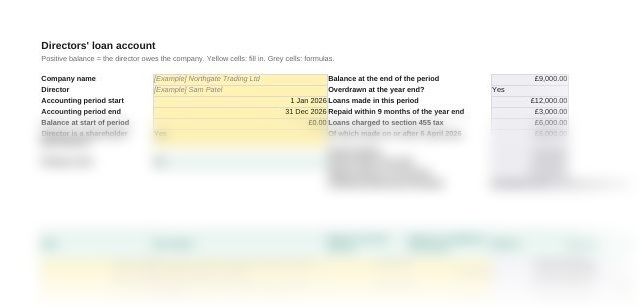
What the schedule looks like
When you need it
HMRC expects a company to keep a record of all money a director borrows from or pays into it. That record is the directors' loan account, and any balance at the year end goes on the balance sheet. Use this schedule when:
- A director draws money that is not salary, a dividend or an expense repayment
- The company pays a director's personal bills, such as a tax bill or a car
- You are preparing year-end accounts and need the balance owed by or to each director
- An overdrawn balance has to be cleared, or taxed, within nine months of the year end
How to use the directors' loan account template
- Fill in the yellow cells at the top. Company, director, the accounting period dates, the opening balance and whether the director holds shares.
- Enter each amount on its own row. Money paid to or for the director in one column, money paid in or credited in the other, in date order.
- Clear the Check column. Every row should show OK. Fix any date outside the period or row with two amounts.
- Add repayments after the year end. List them in the table on the right with the date paid. Only those within nine months reduce the tax.
- Use the results in the accounts. Take the year-end balance to the balance sheet, the loan and tax to form CT600A, and note any year over £10,000 for the director's benefit in kind. For a second director, copy the sheet.
Questions
What is a directors' loan account?
The record of all money a director takes from the company that is not salary, a dividend or an expense repayment, and all money the director pays in or lends to the company. Any balance at the year end goes on the balance sheet in the annual accounts.
What happens if a directors' loan account is overdrawn at the year end?
If the director repays it within nine months of the end of the accounting period, no extra corporation tax is due. Any part still owed after that is charged to section 455 tax, which the company pays nine months and one day after the period ends.
What is the section 455 tax rate?
35.75% for loans made on or after 6 April 2026 and 33.75% for loans made from 6 April 2022 to 5 April 2026. The rate depends on the date the loan was made, so one balance can be charged at both rates.
Can the company get section 455 tax back?
Yes, once the loan is repaid, released or written off. The claim can be made from nine months and one day after the end of the accounting period in which that happened, and within four years.
What is the £10,000 rule for directors' loans?
If a shareholder-director owes the company more than £10,000 at any time in the tax year, the company treats the loan as a benefit in kind. It is reported for the director and Class 1 National Insurance is due.
What does it mean if the account is in credit?
The company owes the director money, for example from expenses or dividends credited to the account. It shows as a negative balance in the schedule and no section 455 tax arises.
Also in the company secretarial pack
Who it's for
Accountancy practices preparing year-end accounts for owner-managed companies, and directors who keep their own loan account.
Last checked
Checked against HMRC's guidance on directors' loans, the Company Taxation Manual and the Corporation Tax Act 2010 in November 2026.