
Transfer pricing local file template for UK group companies
Document the local entity, each material category of controlled transactions and the financial information behind them, in the order the OECD Guidelines set out. This transfer pricing local file template is one Word document for a UK company in a large multinational group, with a repeatable block for each category.
Finance teamsGet this pack and 51 more for $79
Want every pack, for every region? Global library, 110 packs, $99
What the Local File looks like
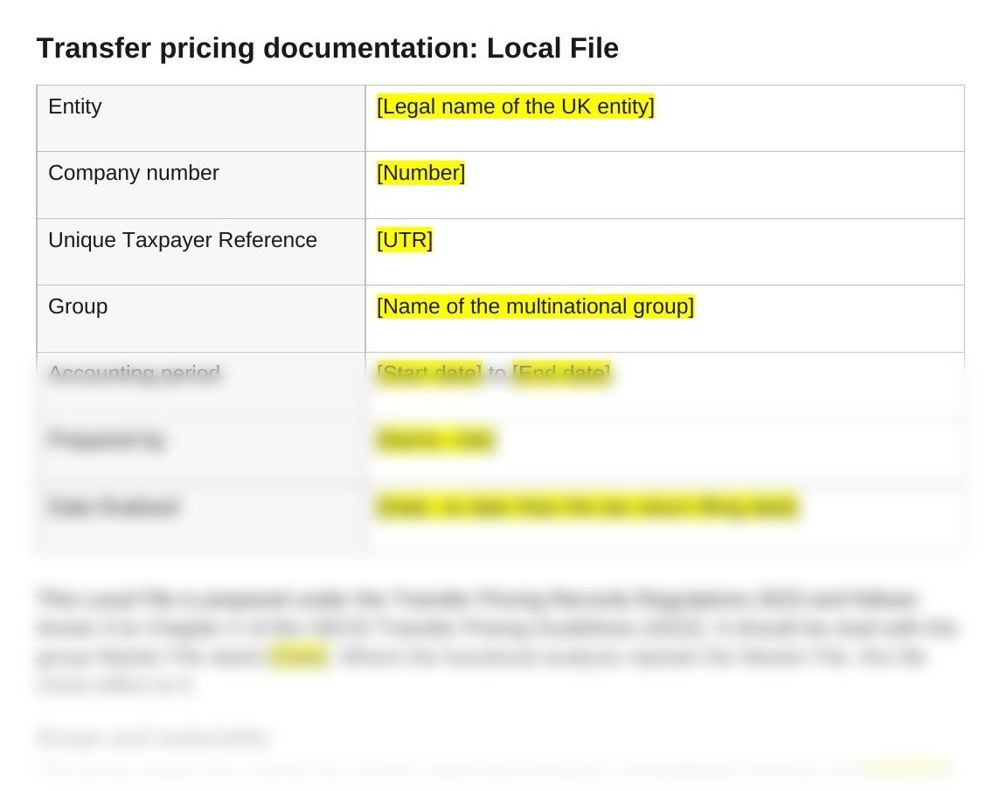
When you need a transfer pricing local file template
Under the UK Transfer Pricing Records Regulations 2023, a UK company in a multinational group that meets the country-by-country reporting threshold of €750 million in group revenue must keep a Master File and a Local File. The rules apply to accounting periods beginning on or after 1 April 2023, and the Local File follows Annex II to Chapter V of the OECD Transfer Pricing Guidelines. Use the template when:
- Your group's consolidated revenue is €750 million or more and it has a UK company
- You are preparing the Local File before the company's tax return filing date
- HMRC has asked for the transfer pricing records and you need them ready to send
- A restructuring or transfer of intangibles affected the UK entity this year or last year
- You prepare transfer pricing documentation for several UK subsidiaries and want the same layout for each
How to use the transfer pricing local file template
- Fill in the cover table. Entity name, company number, UTR, group, accounting period and who prepared the file, and give the date of the group Master File it should be read with.
- Set the scope. Take the material categories from the intercompany transactions register in the pack and list what is left out and why.
- Describe the local entity. Management structure, who local management reports to and where they are based, the business and strategy, any restructuring, and key competitors.
- Repeat Part 2 for each category. Copy sections 2.1 to 2.9 once per material category and fill in the amounts, agreements, functional analysis, method, comparables and conclusion.
- Tie it to the accounts and sign it off. Complete Part 3 so the figures agree to the statutory accounts, attach the appendices and have it approved before the filing date.
Questions
What goes in a transfer pricing Local File?
Under Annex II to Chapter V of the OECD Guidelines, three things: the local entity, each material category of controlled transactions, and the financial information. The template follows that order, part by part.
Which UK companies need a Local File?
Companies in a multinational group that meets the country-by-country reporting threshold of €750 million in consolidated revenue, for accounting periods beginning on or after 1 April 2023. A company with no controlled transactions to report has nothing to keep.
When must the Local File be ready?
HMRC expects it to be finalised no later than the filing date of the company's tax return for the period. The group Master File should be reviewed by the return due date for the ultimate parent.
Which transactions count as material?
HMRC accepts a threshold of £1 million effect on UK taxable profits for each category. Some categories are material because of their nature whatever their size, such as profit split pricing, transfers of intangibles, strategic or leadership services, cost contribution arrangements and business restructurings.
What can be left out of the Local File?
Transactions between UK companies in the group, unless a company has a patent box election or a ring-fenced trade, and transactions covered by an advance pricing agreement made on or before 31 March 2023.
How long do you have to send it to HMRC?
HMRC generally treats 30 days after an information notice as a reasonable time to provide the records, so the file should be finished and ready before any request.
Also in the transfer pricing pack
Who it's for
Group finance and tax teams of multinational groups with UK entities, and the advisers who prepare their documentation.
Last checked
Checked against the Transfer Pricing Records Regulations 2023, HMRC's International Manual and the 2022 OECD Transfer Pricing Guidelines in November 2026.




