Section 7216 consent form template for tax preparers
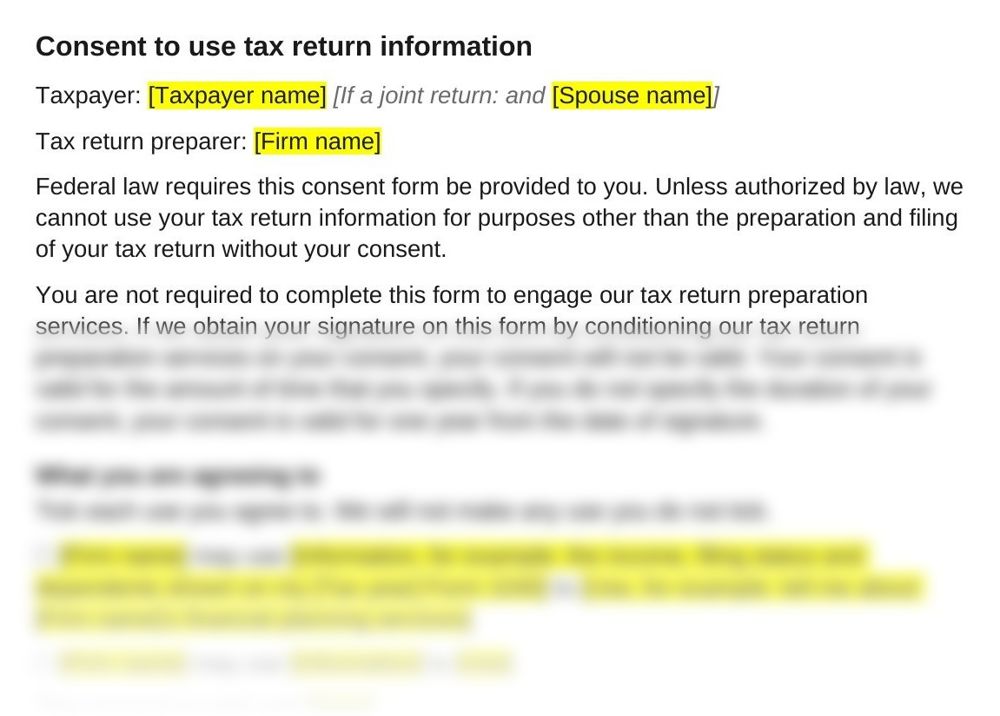
Get the client's written consent before you use their tax return information for anything other than preparing the return, with the wording the IRS requires. This 7216 consent form template is one Word form for consent to use, set in 12-point type on letter-size paper.
US firmsGet this pack and 45 more for $69
You save $546 on buying them one by one
Buy the US library · $69Want every pack, for every region? Global library, 101 packs, $129
What the form looks like
When you need a 7216 consent form template
Section 7216 of the Internal Revenue Code makes it an offence for a tax return preparer to use or disclose tax return information without authority. Where the regulations don't already allow it, you need the client's signed consent before the use or disclosure. The kit has three consent forms: this consent to use, a consent to disclose, and a consent to disclose to a software or AI provider.
- You want to use return information to tell clients about other services, such as financial planning
- You send a copy of a return to a lender or other third party at the client's request (consent to disclose)
- You share client documents with a software or AI provider that helps prepare returns, including one outside the United States (provider consent)
- An earlier consent has reached its end date
How to use the 7216 consent form template
- Pick the right form. Consent to use and consent to disclose must be separate documents, so use the form that matches what you plan to do.
- Describe each use. Name the information and the purpose. Add one tick box per use, and only make the uses the client ticks.
- Fill in every field before signing. Include the end date. Don't change the mandatory statements or the form after the client signs.
- Print it as set. Keep the 12-point type on letter-size paper.
- Give the client a copy. Hand over a copy of the signed form at the time of signing and keep the original on file.
Questions
What is a 7216 consent form?
A written consent the client signs to let their tax return preparer use or disclose their tax return information for a purpose the regulations don't already allow, such as marketing other services or sending a return to a lender.
When is a 7216 consent required?
Before the preparer uses or discloses the information. Consent can't be given after the event. A preparer also can't ask for consent to use information for unrelated marketing after handing the client the completed return to sign.
What are the format rules for a 7216 consent?
Under Rev. Proc. 2013-14, a paper consent must be on paper at least 8.5 by 11 inches, with all text in at least 12-point type. It must include the mandatory statements and the TIGTA notice, and the client must sign and date it.
How long is a 7216 consent valid?
For the period the client sets. If no period is stated, the consent lasts one year from the date the client signed it.
Can consent to use and consent to disclose be on one form?
No. Rev. Proc. 2013-14 requires use consents and disclosure consents in separate documents. One form can cover several uses, or several disclosures, if the client can select each one.
What is the penalty for breaking section 7216?
A knowing or reckless breach is a misdemeanour with a fine of up to $1,000, up to one year in prison, or both. There is also a civil penalty of $250 for each improper use or disclosure under section 6713.
Also in the tax season engagement and consent kit
Who it's for
CPA, EA and tax preparer firms that use or share client return information beyond preparing the return.
Last checked
Checked against 26 CFR 301.7216-3 and Rev. Proc. 2013-14 in November 2026.