
Accountable plan template for S corporations
Repay owners and staff for business expenses they pay personally, without the money counting as wages. This accountable plan template is one Word plan the board adopts once, set out under Treasury Regulation 1.62-2.
US firmsGet this pack and 51 more for $79
Want every pack, for every region? Global library, 110 packs, $99
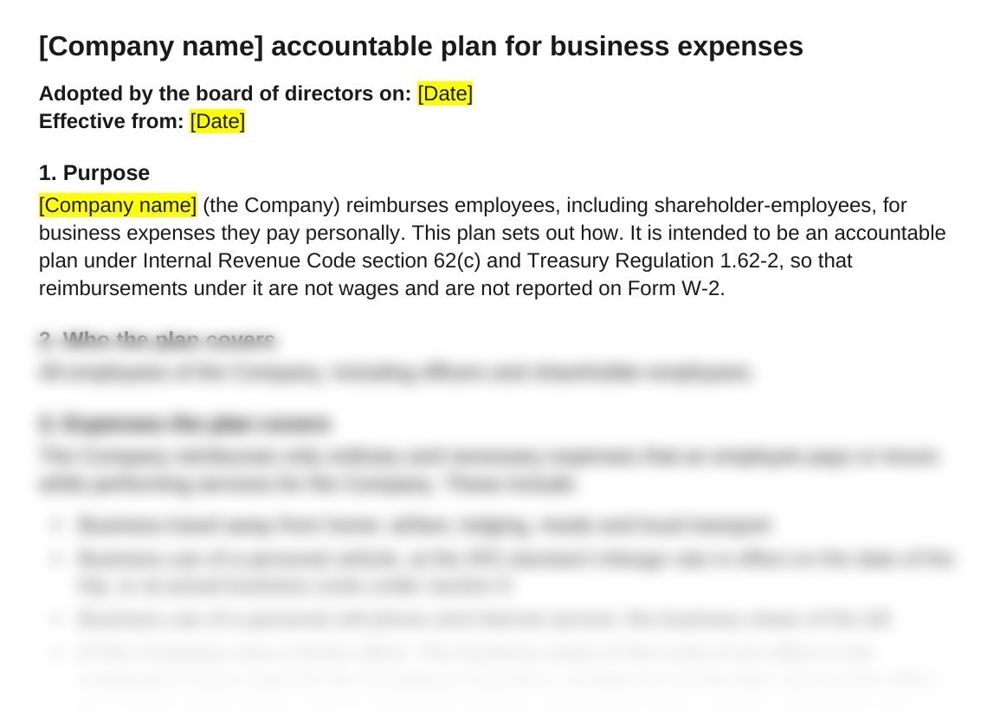
What the plan looks like
Who needs one
Under Treasury Regulation 1.62-2, a reimbursement arrangement is an accountable plan when it has a business connection, requires each expense to be substantiated and requires any excess to be returned within a reasonable period. Payments under it are left off Form W-2 and are free of income tax withholding, FICA and FUTA. A plan helps:
- An S corporation whose shareholder-employees pay business costs personally and claim them back
- An owner who works from home and wants the company to repay the business share of the home office
- A company that pays mileage for business trips in a personal car
- A business that gives travel advances and needs a rule for money not spent
How to use the accountable plan template
- Fill in the company and the dates. Add the company name, the date the board adopts the plan and the date it takes effect.
- Choose the expenses. Keep the home office line if the company repays home office costs, add any other expense type and delete what does not apply.
- Pick how you pay. Either within a set number of business days of an approved report, or with the next payroll as a separate non-wage item.
- Have the board adopt it. The president or secretary signs for the board. Keep the signed plan with the corporate records.
- Run every claim through it. Collect an expense report within 60 days of each expense, with receipts for lodging and anything of $75 or more, and get any unspent advance back within 120 days.
Questions
What is an accountable plan?
An arrangement under which an employer repays employees for business expenses they have substantiated and gets back any excess. Treasury Regulation 1.62-2 sets three tests: a business connection, substantiation within a reasonable period, and return of amounts above the substantiated expenses. Payments that meet them are not wages.
Does an accountable plan need to be in writing?
Treasury Regulation 1.62-2 does not require a written document. A written plan adopted by the board shows the rules were in place before reimbursements were paid, and gives owners and staff one set of rules to follow.
What are the 60-day and 120-day rules?
They come from the fixed date safe harbor in the regulation. An advance paid within 30 days before an expense, an expense substantiated within 60 days after it is paid or incurred, and an excess returned within 120 days after the expense all count as within a reasonable period. The plan uses these three limits.
What happens to reimbursements outside an accountable plan?
They are treated as paid under a nonaccountable plan. They go in the employee's gross income, are reported as wages on Form W-2 and are subject to income tax withholding, FICA and FUTA. The same applies to any amount an employee does not substantiate or return in time.
Can an S corporation owner use an accountable plan?
Yes. A shareholder who works for the corporation is paid wages as a shareholder-employee, and this plan covers all employees, including officers and shareholder-employees. Home office, phone and mileage costs repaid under the plan stay off the owner's W-2.
What mileage rate goes in the plan for 2026?
The IRS business standard mileage rate is 72.5 cents a mile from January 1 to June 30, 2026 and 76 cents a mile from July 1 to December 31, 2026. The plan sets out both, and the employee keeps a log of date, destination, purpose and miles for each trip.
Also in the s corporation owner pay pack
Who it's for
CPA firms, enrolled agents and bookkeepers who look after S corporation owners, and small companies that repay staff expenses.
Last checked
Checked against Treasury Regulations 1.62-2 and 1.274-5 and the IRS standard mileage rates for 2026 in November 2026.




