MTD client letter template for April 2027 and 2028
Tell each sole trader and landlord client why Making Tax Digital for Income Tax applies to them, what changes, what you will do and what you need from them. This MTD client letter is one Word letter for the April 2027 start, with a second version in the pack for clients starting in April 2028.
UK practicesGet this pack and 100 more for $129
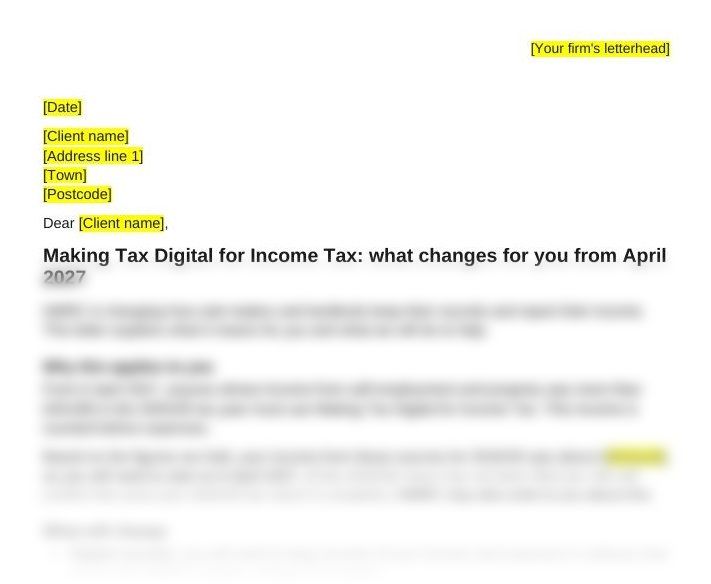
What the letter looks like
When to send it
Send the April 2027 letter to every client whose self-employment and property income was over £30,000 in the 2025/26 tax year. Send the April 2028 version to clients over £20,000 in 2026/27. The pack's readiness tracker works out who gets which.
- A sole trader or landlord client crosses £30,000 of qualifying income in 2025/26
- You have their 2025/26 figures and want to warn them before HMRC writes
- A client below the April 2027 level will start in April 2028 and wants time to get used to software
- You are changing your fees for the quarterly work and need to tell clients in good time
How to use the MTD client letter
- Check the start date first. Qualifying income is turnover from self-employment and property before expenses. Use the April 2028 letter for clients between £20,000 and £30,000.
- Enter the client's income. Add the 2025/26 figure you hold. Keep the optional line if their return is not filed yet.
- Pick the quarterly line. Choose whether you send the quarterly summaries or check the client's records and send them.
- Choose the fees wording. Promise a revised engagement letter, or state the new fee. The pack's fee and engagement wording covers the engagement letter itself.
- Set a reply date. Ask the client to book a meeting to choose software, and record the letter in the tracker.
Questions
Who needs to use MTD for Income Tax from April 2027?
Sole traders and landlords whose qualifying income was over £30,000 in the 2025/26 tax year. Qualifying income is turnover from self-employment and property, before expenses. From April 2028 the level drops to £20,000, based on 2026/27.
What income counts towards the MTD threshold?
Self-employment and property income before expenses. A partner's share of partnership profit, employment income, pensions and dividends, including those from the client's own company, do not count.
What are the MTD quarterly deadlines?
7 August, 7 November, 7 February and 7 May, for the standard quarters that run from 6 April. Clients with a 1 April to 31 March year can use calendar quarters with the same deadlines.
Do clients pay tax every quarter under MTD?
No. The quarterly summaries are not tax returns or payments. Tax is still due by 31 January and, for clients who make payments on account, 31 July.
What happens if a client misses a quarterly deadline?
In the 2026/27 tax year there are no penalty points for late quarterly summaries. After that, each missed deadline earns a point, and four points bring a £200 penalty.
Can a client be exempt from MTD?
Yes, if they are digitally excluded. They apply to HMRC by phone or in writing, and agents can apply for clients through the Agent Dedicated Line. HMRC aims to reply within 28 days.
Also in the MTD for Income Tax pack
Who it's for
Practices with sole trader and landlord clients who join MTD for Income Tax in April 2027 or April 2028.
Last checked
Checked against HMRC's MTD for Income Tax guidance in November 2026.