Lease schedule template in Excel for every lease you hold
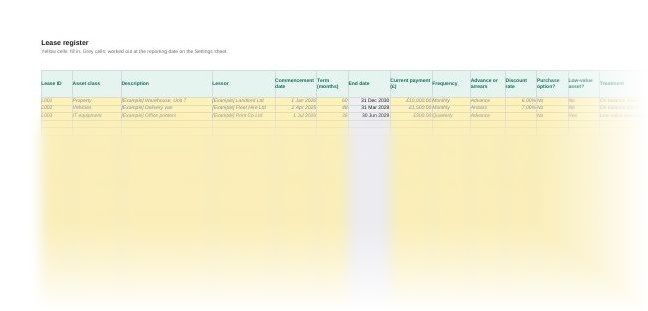
Keep one list of every lease the company holds as lessee, with its dates, payments and treatment, and see what is still to pay and which break notices are coming up. This lease schedule template is one Excel register with totals by asset class, commitments for exempt leases and a check on every row.
Finance teamsGet this pack and 35 more for $79
Want every pack, for every region? Global library, 110 packs, $99
What the register looks like
When you need a lease schedule
A lease schedule is the list of every lease a company holds, with the terms needed to account for it and to manage it. Under IFRS 16 and the revised FRS 102 Section 20, which applies to accounting periods beginning on or after 1 January 2026, most leases go on the balance sheet, so the list has to be complete. Use this one when:
- Your company is moving to the revised FRS 102 Section 20 and needs to find every lease first
- Leases are spread across property, fleet and IT, and nobody holds one list
- The auditor asks how you know no lease has been missed
- A break clause passed last year because nobody tracked the notice date
How to use the lease schedule template
- Fill in Settings. Enter the reporting date and how many days' warning you want before a break notice deadline. Today's date fills itself in.
- Add one row per lease. Enter the asset class, lessor, commencement date, term, current payment, frequency and whether it is paid in advance or arrears.
- Choose the treatment. On balance sheet, short-term exemption or low-value exemption. The Check column flags a treatment the lease does not qualify for.
- Copy in the calculator figures. For each lease on the balance sheet, enter the lease liability and right-of-use asset at the reporting date from the lease calculator.
- Add break dates and read the Summary. Enter any break date and notice period, then use the Summary totals and payment bands for the lease note.
Questions
What is a lease schedule?
A list of every lease a company holds, with the asset, lessor, dates, payments and accounting treatment. It is where lease accounting starts, because a lease that is not on the list does not get into the accounts.
What is a short-term lease?
A lease that, at the commencement date, has a lease term of 12 months or less. A lease with a purchase option is not short-term. IFRS 16 and FRS 102 use the same definition.
Can a car be a low-value asset?
No. FRS 102 lists cars, vans, trucks, forklifts, land and buildings and production line equipment among the assets that are not of low value, so the register flags a low-value exemption on any vehicle.
What lease commitments must be disclosed?
Under FRS 102, a lessee that uses the short-term or low-value exemption discloses those commitments separately for three periods: not later than one year, one to five years and later than five years. Under IFRS 16 a lessee gives a maturity analysis of lease liabilities.
When does the new FRS 102 lease accounting start?
For accounting periods beginning on or after 1 January 2026. Early application is allowed if all the 2024 amendments are applied at the same time.
Also in the lease accounting pack
Who it's for
Finance teams of companies that lease property, vehicles or equipment and report under IFRS or FRS 102.
Last checked
Checked against IFRS 16 and FRS 102 Section 20 as revised by the 2024 periodic review in November 2026.