CSRD scoping pack after the Omnibus
A scoping test built on the final Omnibus thresholds in Directive (EU) 2026/470, a readiness checklist and a board briefing note. Find out if you report, from which year, and what to tell the board.
EU firmsGlobal library · 101 packs
Get this pack and 100 more for $129
CSRD scoping · this packAML complianceCharity accountsEstate administrationMTD for Income TaxP11D and payrollingUK SRS readinessCarbon reduction planCIS+ 92 more
What's inside
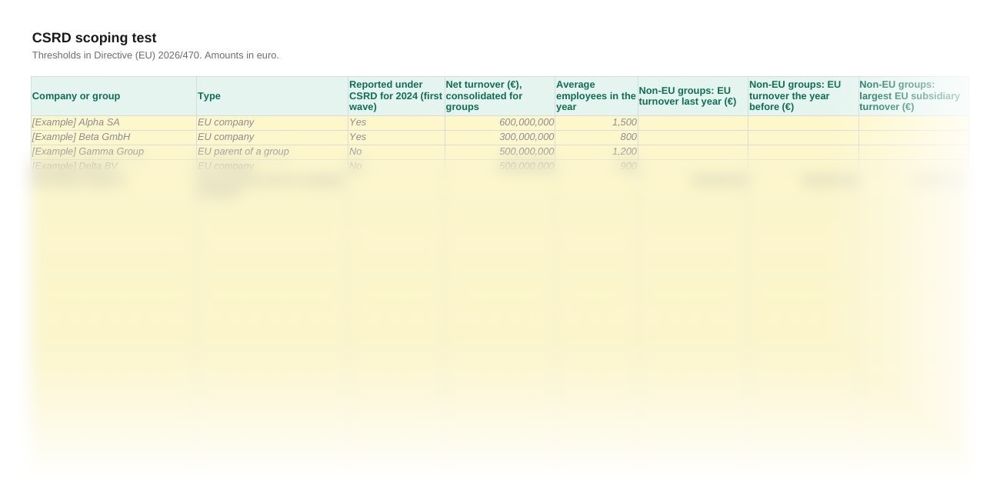
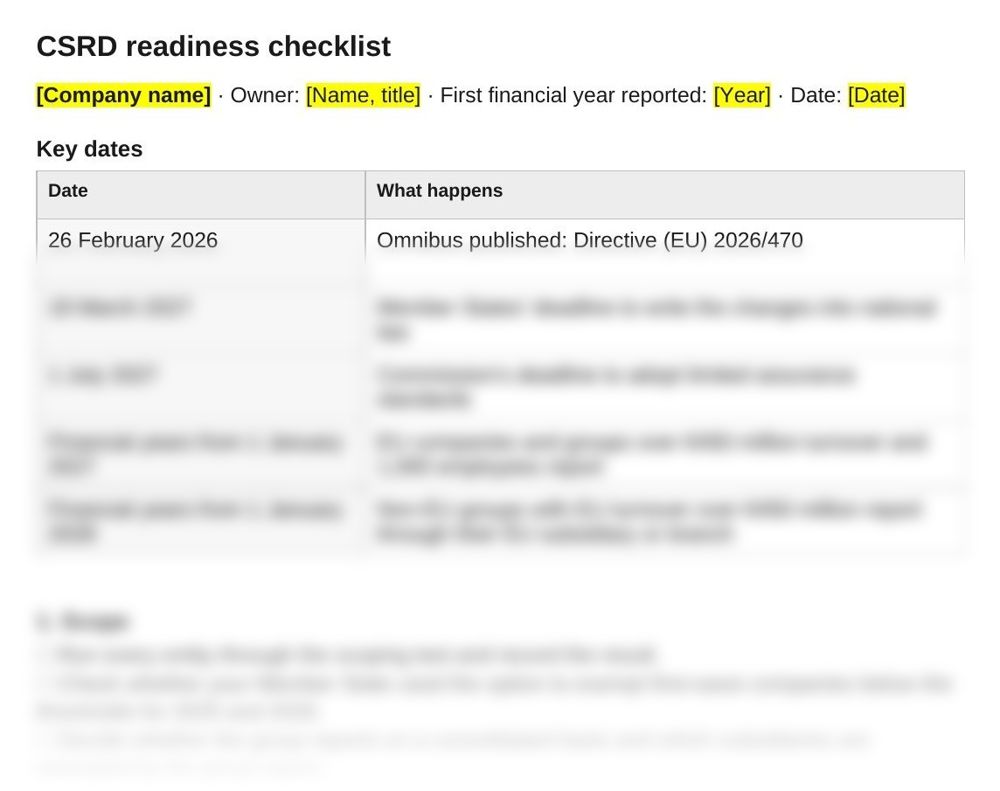
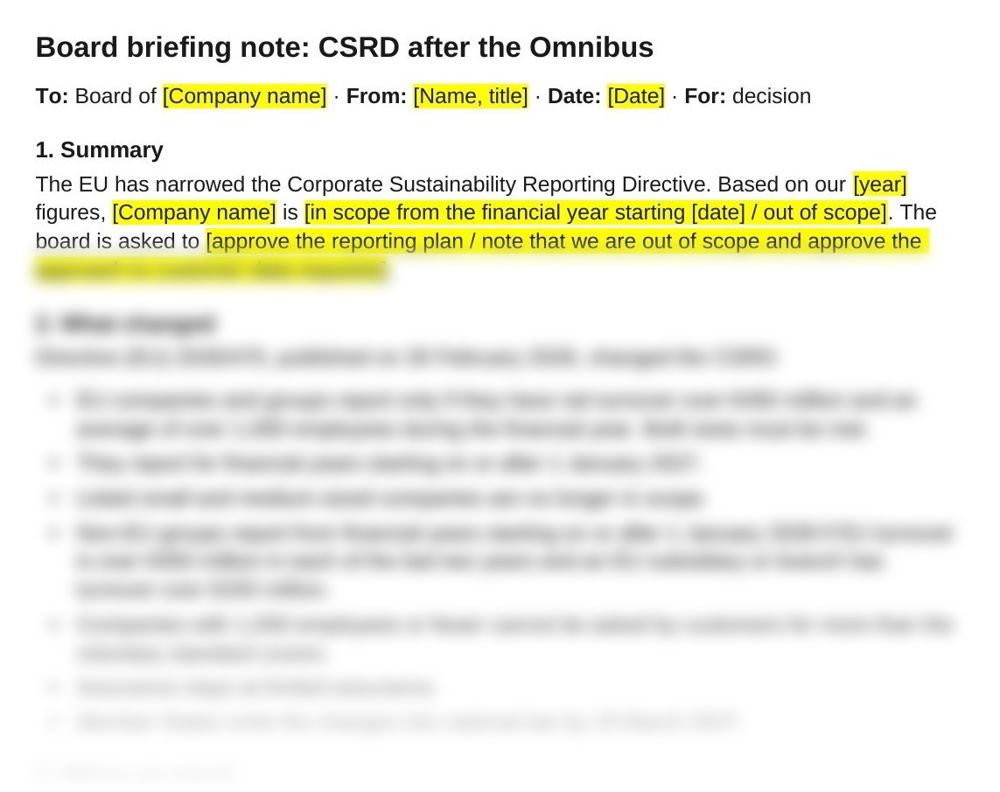
First page of each document. 4 files, Word and Excel.
What the Omnibus changedDocument in the pack
Over €450 million turnover and over 1,000 employeesDirective (EU) 2026/470, Art. 3
✓CSRD scoping testTests each company and group on both thresholds
Reporting from financial years starting 1 January 2027Directive (EU) 2022/2464, Art. 5(2)
✓CSRD scoping testShows the first year each entity reports
First-wave companies below the thresholdsArt. 5(2), derogation
✓Board briefing noteWhether 2025 and 2026 reports are still due
Non-EU groups from 2028Directive 2013/34/EU, Art. 40a
✓CSRD scoping test€450 million EU turnover and €200 million subsidiary or branch
Limits on value chain requestsDirective (EU) 2026/470
✓CSRD scoping testLists protected suppliers with 1,000 employees or fewer
Limited assuranceDirective 2006/43/EC, Art. 26a
✓Readiness checklistAssurance provider, scope and timetable
A board that knows where the company stands
✓Board briefing noteSummary, figures and decisions
Who it's for
Finance and sustainability leads at EU companies and groups, CFOs of non-EU groups with EU subsidiaries, and the firms that advise them.
Last checked
Checked against Directive (EU) 2026/470 (Omnibus I), Directive (EU) 2025/794 and Directive (EU) 2022/2464 in November 2026.