
Audit planning memorandum template for ISA (UK) audits
Record the overall audit strategy and audit plan in one place before fieldwork starts, and get the engagement partner's sign-off. This audit planning memorandum template is a four-page Word document with eleven sections, from acceptance and independence to approval, and it sits next to the audit programme workbook.
UK practicesGet this pack and 51 more for $79
Want every pack, for every region? Global library, 110 packs, $99
What the memorandum looks like
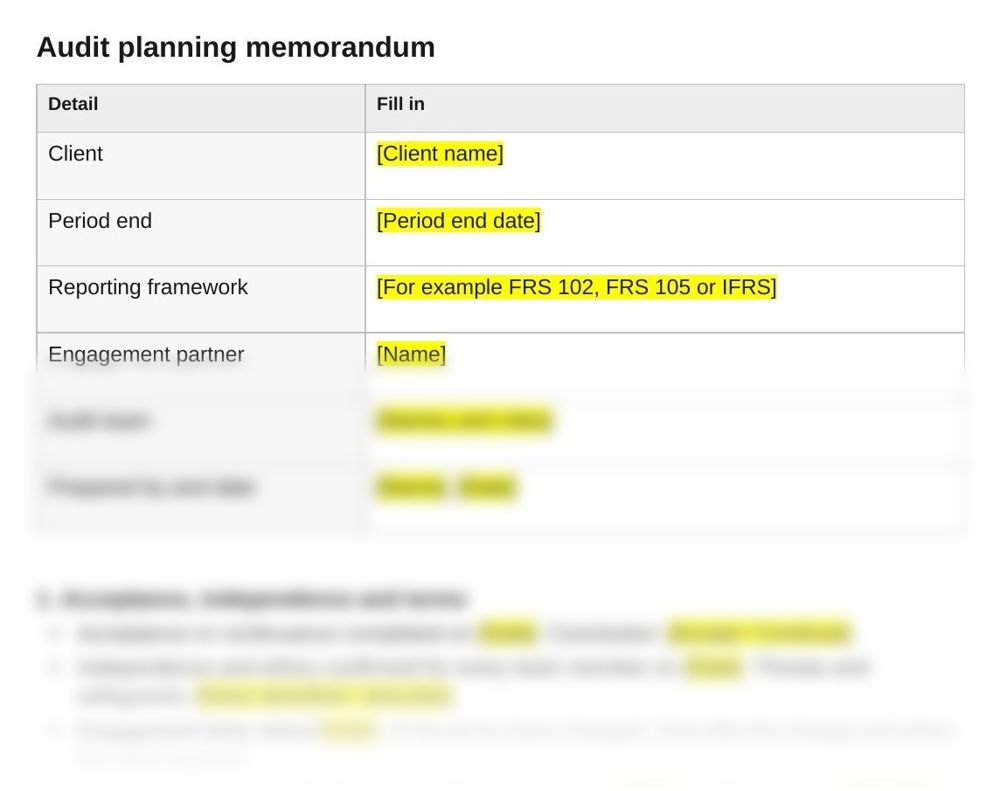
When to use the audit planning memorandum template
ISA (UK) 300 asks the auditor to set an overall audit strategy and an audit plan, to change them as needed during the audit, and to document both along with any significant changes and the reasons. The engagement partner reviews the strategy and the plan. Use the memorandum:
- At the planning stage of every statutory audit, before fieldwork starts
- For a first-year audit, where acceptance and contact with the previous auditor are recorded
- After the team discussion, to record who attended and the points raised
- During the audit, when materiality, a risk or the approach to an area changes
How to fill in the memorandum
- Fill in the engagement details. Client, period end, framework, partner and team, and the dates for the planning meeting, count, fieldwork, review, signing and filing.
- Set materiality. Enter materiality, performance materiality and the clearly trivial amount, with the benchmark, the percentages your firm uses and why they fit.
- Hold and record the team discussion. The engagement partner and key team members discuss where the accounts could be materially misstated, including by fraud.
- List the risks and responses. Keep management override, state the revenue streams at risk or why the presumption is rebutted, and add any other significant risk with tests of details.
- Plan each area and get approval. Set risk and approach by area in line with the audit programme tabs, then have the engagement partner sign. Record any later change with the date and reason.
Questions
What is an audit planning memorandum?
A document recording the overall audit strategy and audit plan: scope, timing, materiality, risks, the planned response by area and how the team is supervised. ISA (UK) 300 asks for both to be documented.
Who approves the audit plan?
The engagement partner reviews the overall audit strategy and the audit plan. The memorandum ends with the preparer's and the engagement partner's names and dates.
Is management override always a significant risk?
Yes. ISA (UK) 240 says the risk is present in all entities and treats it as a significant risk. The response includes testing journal entries made at the period end and after closing, and reviewing estimates for bias.
Does revenue recognition always have to be a fraud risk?
ISA (UK) 240 presumes risks of fraud in revenue recognition, but the presumption may be rebutted. The memorandum asks you to name the revenue streams at risk or record why it is rebutted.
Can materiality change during the audit?
Yes. ISA (UK) 320 says materiality is revised when you learn something that would have led to a different amount at the start. The memorandum notes it will be revisited when the final figures are in.
What period should the going concern assessment cover?
Under ISA (UK) 570, if management's assessment covers less than twelve months from the date the financial statements are approved, the auditor asks management to extend it to at least twelve months.
Also in the audit programme
Who it's for
Audit firms and sole practitioners planning statutory audits of small and mid-sized companies under ISAs (UK).
Last checked
Checked against ISAs (UK) 220, 240, 300, 315, 320 and 570 on the FRC website in November 2026.




