Agreed-upon procedures engagement letter template (AT-C 215)
Agree the procedures, the intended purpose, who will use the report and what it will say before you start an AUP engagement. This agreed-upon procedures engagement letter is one Word letter with every term AT-C 215 lists, a procedures appendix and an acknowledgment page for the engaging party to sign.
US firmsGet this pack and 45 more for $69
You save $546 on buying them one by one
Buy the US library · $69Want every pack, for every region? Global library, 101 packs, $129
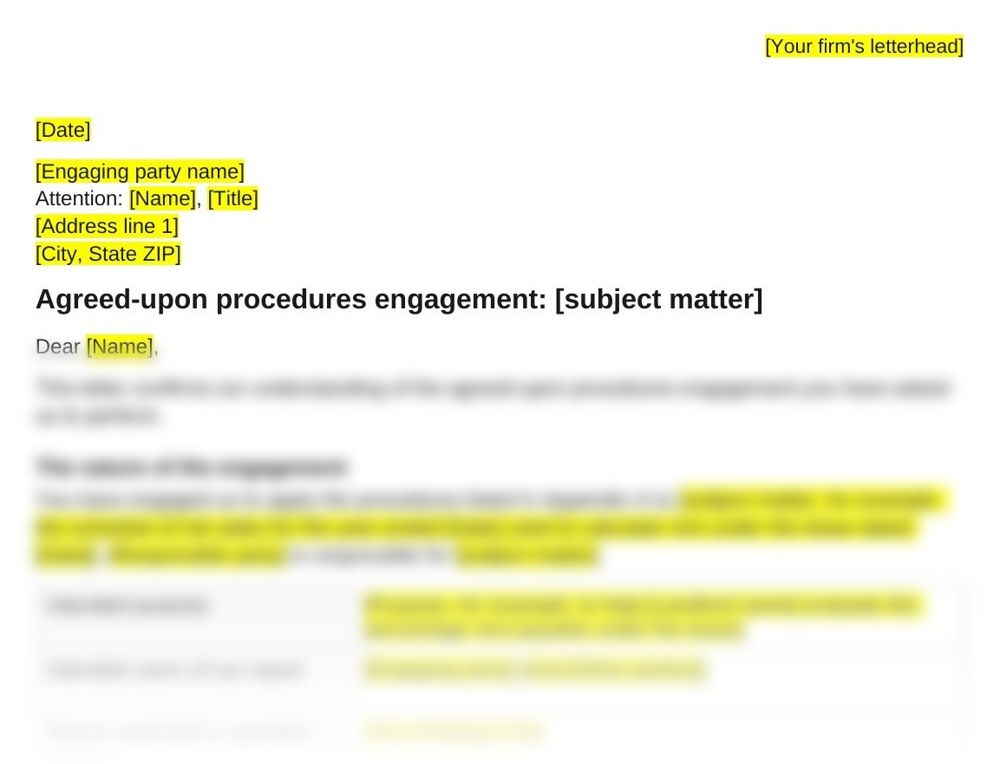
What the letter looks like
When to send it
AT-C 215 requires you to agree the terms of an agreed-upon procedures engagement in an engagement letter or other written agreement, and to get the engaging party's written agreement to the procedures before you issue the report. Send it when:
- A landlord needs net sales tested to work out percentage rent, as in the letter's example
- A lender, grantor or other contract party asks for procedures on a schedule or calculation
- A law or regulation calls for procedures on specific information
- A client wants findings on set questions rather than an audit or review
How to use the agreed-upon procedures engagement letter
- Fill in the engagement table. Intended purpose, intended users, whether the report is restricted, any law or contract behind it and any other parties.
- Write the procedures in Appendix A. Describe each one precisely. Don't use words like check or test unless the procedure defines them.
- Keep or delete the optional lines. A threshold for reporting exceptions, an external specialist, other parties and representations from a separate party.
- Set the date and the fee. Add the billing terms. A change in the procedures means agreeing the fee again first.
- Get both signatures. The signed letter before you start, and the signed acknowledgment of the final procedures before you issue the report.
Questions
What is an agreed-upon procedures engagement?
An attestation engagement in which a CPA performs specific procedures on subject matter and reports the findings without giving an opinion or conclusion. The subject matter can be financial or nonfinancial.
What must an AUP engagement letter include?
AT-C 215 lists the terms: the nature of the engagement, the subject matter and the party accountable for it, your role, that you follow AICPA attestation standards, the engaging party's agreement to give written agreement to the procedures and a representation letter, any other parties, the expected form of the report and any use restriction, disclaimers, assistance, external specialists and thresholds for reporting exceptions.
Can the procedures be set during the engagement?
Yes. You can develop the procedures over the course of the engagement, as long as the engaging party gives written agreement to the procedures performed, and acknowledges they suit the intended purpose, before you issue the report. If they refuse, you withdraw.
Does an AUP report have to be restricted?
No. You agree with the engaging party at the start whether the report will be restricted to specified parties. The letter has wording for either choice.
Can internal auditors perform the procedures?
No. For engagements beginning on or after December 15, 2025, the procedures listed in the report must be performed by the engagement team, not by internal auditors.
How is an AUP engagement different from an audit?
An audit ends in an opinion on the financial statements. In an AUP engagement you report the findings from procedures the engaging party agreed to, with no opinion or conclusion, and the engaging party decides whether those procedures suit its purpose.
Also in the audit and agreed-upon procedures letters
Who it's for
CPA firms in the US that perform agreed-upon procedures engagements for companies, nonprofits and other clients.
Last checked
Checked against AT-C 215 as currently effective, including the SSAE No. 23 amendments, in November 2026.