
Debtor confirmation letter template with reply slip
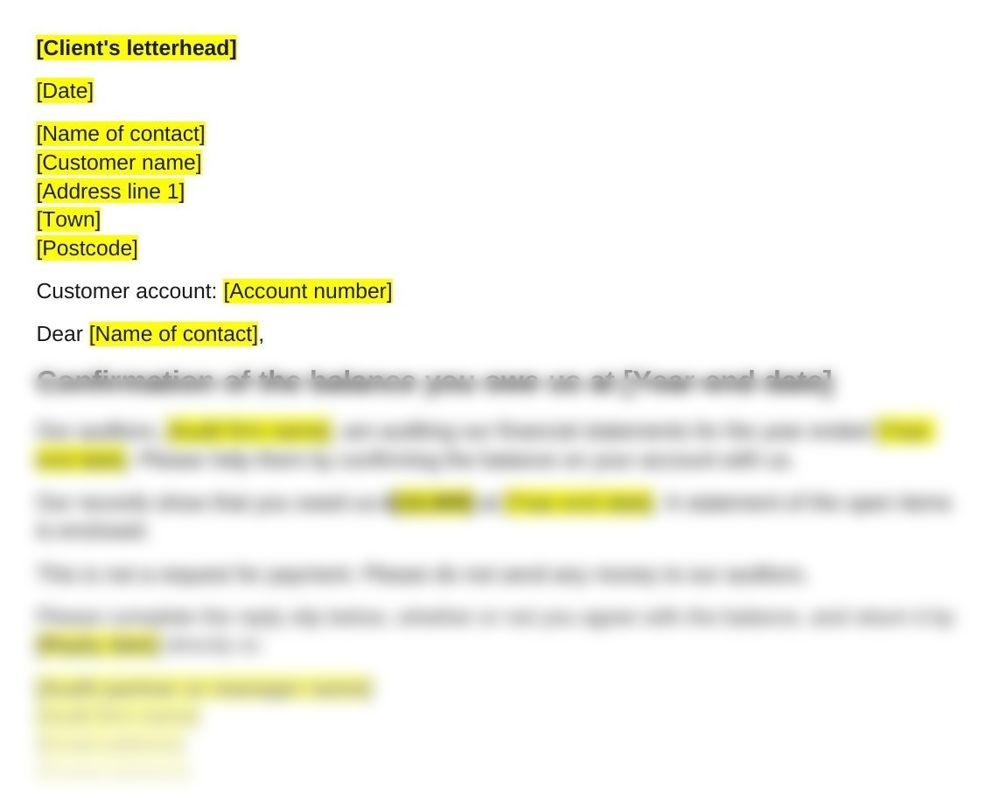
Ask the client's customers to confirm what they owed at the year end, with their answer going straight to the auditor. This debtor confirmation letter template is one Word letter on the client's letterhead, signed by the client, with a reply slip on its own page.
UK practicesGet this pack and 51 more for $79
Want every pack, for every region? Global library, 110 packs, $99
What the letter looks like
When to send a debtor confirmation letter
A debtor confirmation is a positive request: the customer replies in every case, agreeing or giving its own figure. Under ISA (UK) 505 negative confirmations, where a customer replies only if it disagrees, are not allowed in an ISA (UK) audit, so the letter asks for a reply either way. Use it:
- For the customer balances you select for testing at the year end
- When receivables are material and you have assessed a risk on existence
- For large or old balances, credit balances and accounts with related parties
- Again as a follow-up when the first request gets no reply
How to use the debtor confirmation letter template
- Put it on the client's letterhead. The letter comes from the client to its customer, which gives the customer the authority to reply to you.
- Fill in the balance from the ledger. Customer name, account number, year-end balance and a statement of the open items behind it.
- Add your details as the reply address. The audit partner or manager, email and postal address, and a reply date. Check the customer's address before sending.
- Get it signed and send it yourself. The finance director signs. Your firm posts or emails it so the client doesn't handle it after you have selected it.
- Record and follow up. Log each request in the confirmation tracker, chase non-replies and look into every difference.
Questions
What is a debtor confirmation letter?
A letter asking a customer of the audited company to confirm to the auditor how much it owed at the year end. It is one of the main audit tests on the existence of receivables.
Can I use a negative confirmation instead?
Not in an audit under ISAs (UK). ISA (UK) 505 prohibits negative confirmations, so the customer is asked to reply whether or not it agrees.
What if a customer doesn't reply?
Send a follow-up after checking the address. If there is still no reply, carry out alternative procedures for that balance, such as checking cash received after the year end, shipping documents and sales near the year end.
What if the customer's figure is different?
Investigate it. Many differences are timing, such as cash or goods in transit at the year end, but each one is looked at to decide whether the books are wrong.
Can the reply come back through the client?
Ask for it to come directly to the auditor. A reply received through the client raises doubts about its reliability, and an oral reply on its own is not an external confirmation.
Also in the audit confirmation letters
Who it's for
Audit firms and audit teams confirming trade receivables under ISAs (UK), and finance teams sending them for their auditor.
Last checked
Checked against ISA (UK) 505 (Revised October 2023) in November 2026.




